FEMA now lets you buy NFIP flood insurance online at FloodSmart.gov without an agent. Here’s how it works, what it covers, the 30-day wait and why the Dec. 11 deadline matters.
November 5, 2026
Home improvement · Real estate · Life around the house
FEMA now lets you buy NFIP flood insurance online at FloodSmart.gov without an agent. Here’s how it works, what it covers, the 30-day wait and why the Dec. 11 deadline matters.
 Mai
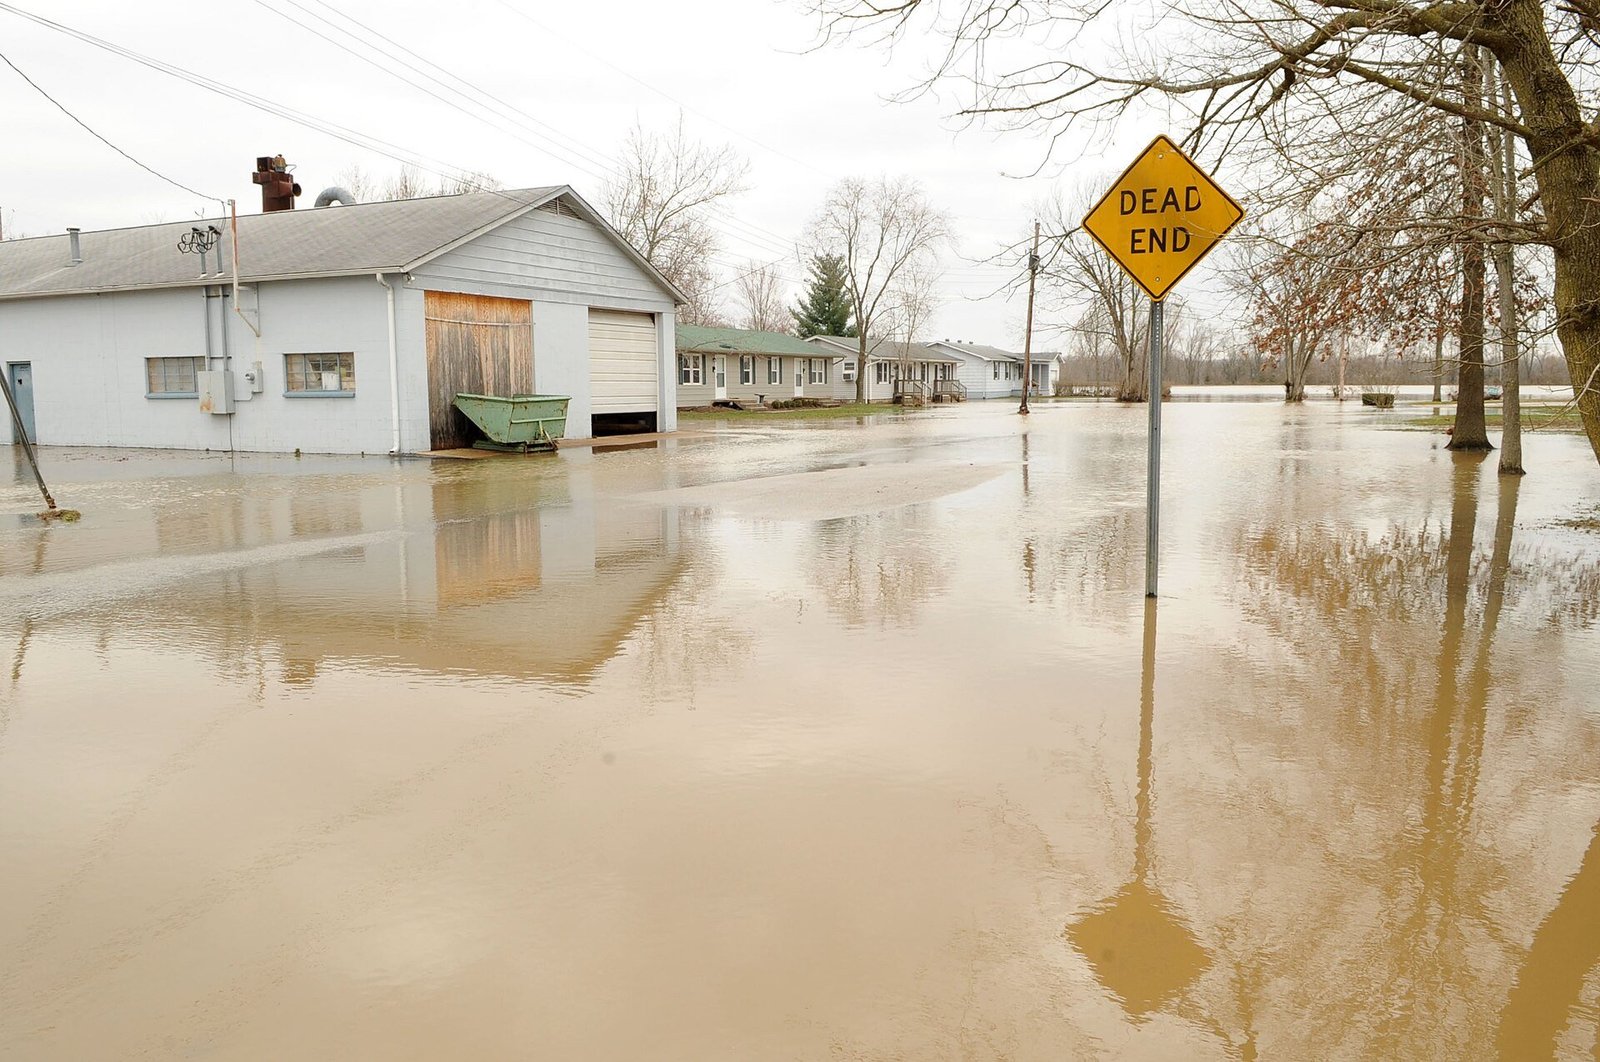
Table of Contents
ToggleYes, you can now buy federal flood insurance entirely online, with no agent required. On Oct. 20, 2026, FEMA launched a self-service purchase option on FloodSmart.gov that lets homeowners and renters get a National Flood Insurance Program (NFIP) quote and pay for a policy in one sitting. It’s open to anyone in the almost 22,700 communities that take part in the NFIP.
The timing matters for two reasons. Coverage usually doesn’t start until 30 days after you buy, and the NFIP’s legal authority to sell new policies is set to expire on Dec. 11, 2026, unless Congress extends it. Add NOAA’s forecast for a wetter-than-average winter across much of the country, and this is a good month to check whether your home needs flood coverage.
Until now, most people bought NFIP policies through an insurance agent who works with one of the program’s partner insurers. FEMA released an online quoting tool in November 2024, but you still couldn’t finish the purchase online, according to the Association of State Floodplain Managers.
The new tool closes that gap. After you answer a few questions about your building, you get a quote and choose one of two paths:
“With this new digital tool, you can get a quote and buy a flood insurance policy in a matter of minutes,” FEMA Administrator Cameron Hamilton said in the agency’s announcement.
One thing the tool doesn’t change is the price. FloodSmart notes that the NFIP’s partner insurers and agents all use the same pricing approach, so every one of them offers the same rate for the same property. Buying online is about convenience, not a discount.
NFIP coverage generally takes effect 30 days after the purchase date. There are a few exceptions, such as no wait when you buy the policy as part of making, increasing, extending or renewing a mortgage, and a one-day wait if your property was just mapped into a high-risk flood zone and you buy within 12 months. For most homeowners buying on their own, though, a policy bought in early November won’t cover a flood until early December. You can’t wait until a storm is in the forecast.
Congress has to renew the NFIP’s authority periodically. The latest extension, signed Sept. 2, 2026, runs to 11:59 p.m. on Dec. 11, 2026, according to FEMA’s reauthorization page. If that authority lapses, FEMA says it would still pay valid claims with available funds, but it would stop selling and renewing policies. Existing policies stay in force until their term ends. Congress has usually extended the program before past deadlines, but there’s no guarantee, so buying before Dec. 11 removes that uncertainty.
NOAA’s 2026-27 U.S. Winter Outlook says a strong El Niño is likely to bring wetter-than-average conditions from California to Florida and along the Eastern Seaboard between December and February. National Weather Service director Ken Graham warned that “too much precipitation on dry soil can fuel destructive flash floods and mudslides.” If you live in one of those areas, your flood risk this winter may be higher than usual.
Usually not. FloodSmart states plainly that most homeowners and renters policies don’t cover flood damage, and that only a flood insurance policy will help you recover after a flood. Yet few people carry it: Yahoo Finance, citing FEMA, reports that just 4% of U.S. homeowners have flood insurance, even though 99% of U.S. counties have been affected by flooding since 1996. If you’re already reviewing what drives your premiums, our guide to understanding home insurance costs is a useful companion to this one.
NFIP policies come in two parts that are bought separately and carry separate deductibles:
Just as important is what’s excluded. According to FloodSmart, NFIP policies don’t cover cash and valuable papers, cars, most personal property kept in basements, property outside the building (landscaping, decks, patios, fences, pools and septic systems), or temporary housing while your home is repaired. The cause of the water matters too: a sewer backup caused by a heavy rainstorm can be covered, while one caused by clogged pipes isn’t. Our article on dealing with sewer backups and odors explains how to tell the difference and prevent them.
FloodSmart says you may find savings by elevating your water heater or electrical panel so they’re less likely to be damaged. Simple yard and drainage fixes also reduce the odds of water reaching your foundation in the first place: clean gutters, extend downspouts away from the house, and make sure the ground slopes away from your walls. See our guide to preventing foundation damage with better drainage for practical fixes, and keep belongings you care about out of the basement, since NFIP contents coverage there is limited.
Yes. Since Oct. 20, 2026, FEMA’s NFIP Direct option on FloodSmart.gov lets you get a quote and buy an NFIP policy completely online if you live in a participating community.
No. NFIP rates are the same whether you buy through FloodSmart.gov or any NFIP agent or insurer. Your premium depends on where and how your home is built and what it would cost to replace.
Usually 30 days after purchase. There’s no wait if you buy it while making, increasing, extending or renewing a mortgage, and only a one-day wait in a few special cases, such as a newly mapped high-risk zone.
FEMA says it would keep paying valid claims, but it would stop selling new policies and renewing existing ones until Congress acts. Policies already in force stay active until they expire.
Homeowners can get up to $250,000 for the building and up to $100,000 for contents. Renters can get up to $100,000 for contents.
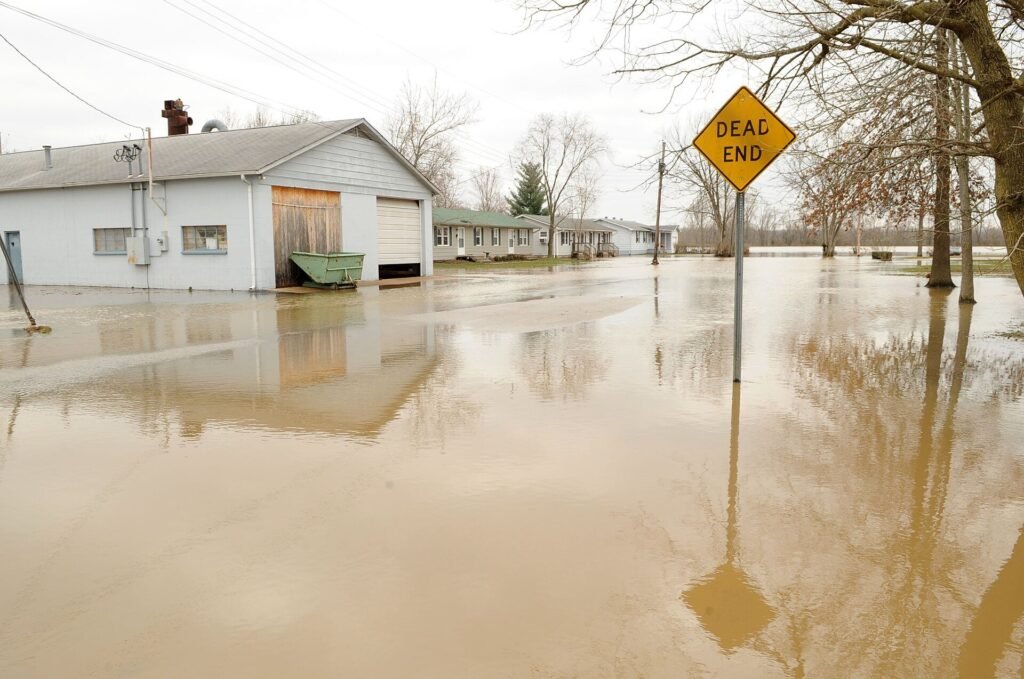
Featured image: Water covers a street near the Meramec River in Pacific, Missouri, March 22, 2008. Photo by Jocelyn Augustino/FEMA, public domain, via Wikimedia Commons.

Mai is Candy Bird's go-to writer for everything around the house, from repairs and DIY fixes to smart storage, energy-saving upgrades and buying or selling a home. Her advice is practical, easy to follow and comes with a touch of humor, whether you're a first-time homeowner or a seasoned DIYer.
More from this writer →
Five minutes, every weekend. Free.
Practical guides for the place you live: fixing it up, decorating it, keeping it running, and buying, selling or renting it.
© 2026 Candy Bird. All rights reserved.
Candy Bird is ad-supported. Our guides are general information, not professional, legal or financial advice: check with a licensed contractor, agent or lender before big decisions.